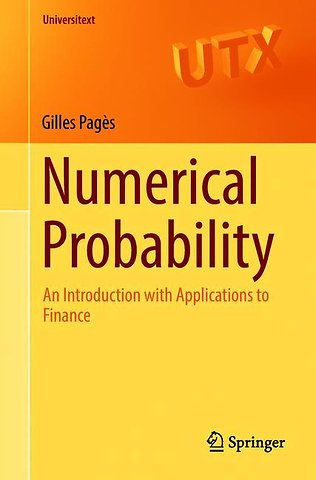
Numerical Probability
An Introduction with Applications to Finance
Paperback Engels 2018 9783319902746Samenvatting
This textbook provides a self-contained introduction to numerical methods in probability with a focus on applications to finance.
Topics covered include the Monte Carlo simulation (including simulation of random variables, variance reduction, quasi-Monte Carlo simulation, and more recent developments such as the multilevel paradigm), stochastic optimization and approximation, discretization schemes of stochastic differential equations, as well as optimal quantization methods. The author further presents detailed applications to numerical aspects of pricing and hedging of financial derivatives, risk measures (such as value-at-risk and conditional value-at-risk), implicitation of parameters, and calibration.
Aimed at graduate students and advanced undergraduate students, this book contains useful examples and over 150 exercises, making it suitable for self-study.
Specificaties
Lezersrecensies



Rubrieken
- advisering
- algemeen management
- coaching en trainen
- communicatie en media
- economie
- financieel management
- inkoop en logistiek
- internet en social media
- it-management / ict
- juridisch
- leiderschap
- marketing
- mens en maatschappij
- non-profit
- ondernemen
- organisatiekunde
- personal finance
- personeelsmanagement
- persoonlijke effectiviteit
- projectmanagement
- psychologie
- reclame en verkoop
- strategisch management
- verandermanagement
- werk en loopbaan