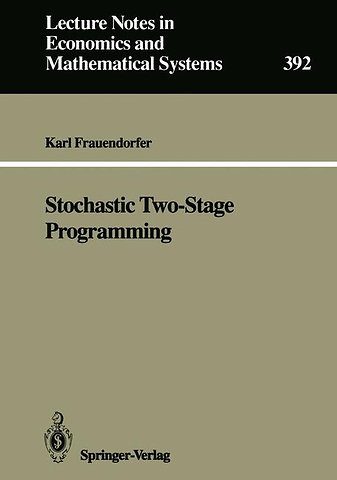
Stochastic Two-Stage Programming
Paperback Engels 1992 9783540560975Samenvatting
Stochastic Programming offers models and methods for
decision problems wheresome of the data are uncertain.
These models have features and structural properties which
are preferably exploited by SP methods within the solution
process. This work contributes to the methodology for
two-stagemodels. In these models the objective function is
given as an integral, whose integrand depends on a random
vector, on its probability measure and on a decision.
The main results of this work have been derived with the
intention to ease these difficulties: After investigating
duality relations for convex optimization problems with
supply/demand and prices being treated as parameters, a
stability criterion is stated and proves
subdifferentiability of the value function. This criterion
is employed for proving the existence of bilinear functions,
which minorize/majorize the integrand. Additionally, these
minorants/majorants support the integrand on generalized
barycenters of simplicial faces of specially shaped
polytopes and amount to an approach which is denoted
barycentric approximation scheme.
Specificaties
Lezersrecensies
Anderen die dit boek kochten, kochten ook
-
 Lee Krajewski€ 90,94
-
Jeroen Moonen€ 14,99
-
Hessel Visser€ 82,95
-
Brigitte Faber-de Lange€ 81,95
-
Gerco Rietveld€ 81,75
-
Kees Gelderman€ 9,95




Rubrieken
- advisering
- algemeen management
- coaching en trainen
- communicatie en media
- economie
- financieel management
- inkoop en logistiek
- internet en social media
- it-management / ict
- juridisch
- leiderschap
- marketing
- mens en maatschappij
- non-profit
- ondernemen
- organisatiekunde
- personal finance
- personeelsmanagement
- persoonlijke effectiviteit
- projectmanagement
- psychologie
- reclame en verkoop
- strategisch management
- verandermanagement
- werk en loopbaan