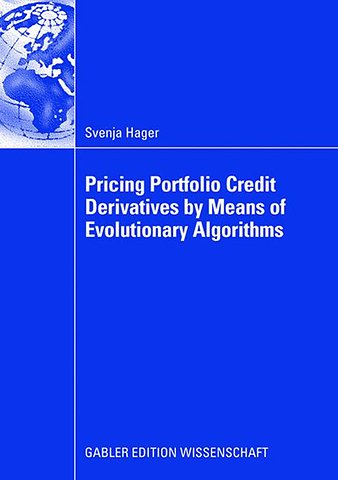
Svenja Hager
Pricing Portfolio Credit Derivatives by Means of Evolutionary Algorithms
Paperback Engels 2008 9783834909152Levertijd ongeveer 9 werkdagen
Gratis verzonden
Samenvatting
Svenja Hager aims at pricing non-standard illiquid portfolio credit derivatives which are related to standard CDO tranches with the same underlying portfolio of obligors. Instead of assuming a homogeneous dependence structure between the default times of different obligors, as it is assumed in the standard market model, the author focuses on the use of heterogeneous correlation structures.
Specificaties
ISBN13:9783834909152
Taal:Engels
Bindwijze:Paperback
Uitgever:Gabler Verlag
Lezersrecensies
Wees de eerste die een lezersrecensie schrijft!




Rubrieken
- advisering
- algemeen management
- coaching en trainen
- communicatie en media
- economie
- financieel management
- inkoop en logistiek
- internet en social media
- it-management / ict
- juridisch
- leiderschap
- marketing
- mens en maatschappij
- non-profit
- ondernemen
- organisatiekunde
- personal finance
- personeelsmanagement
- persoonlijke effectiviteit
- projectmanagement
- psychologie
- reclame en verkoop
- strategisch management
- verandermanagement
- werk en loopbaan